Key Takeaways
- Clear cash flow information is the starting point for sound financing decisions.
- Accessible cash and long-term assets serve different purposes.
- Every borrowing choice has a cost, a risk, and an effect on future cash flow.
- Emergency reserves can reduce reliance on high-cost borrowing after an unexpected expense.
- Insurance-based borrowing requires careful review of policy terms, loan charges, and lapse risk.
- A financing plan should be reviewed when income, family responsibilities, debt, or goals change.
Personal financing works best when it supports a specific purpose instead of becoming a default response to every expense. Whether you are building reserves, paying for a planned purchase, or exploring how to become your own banker with a qualifying whole life policy, the priority is understanding how the decision fits your overall financial life.
A strong plan considers more than income or the size of an account balance. It also considers when money arrives, when bills are due, how much cash is available now, and what obligations could limit future choices.
Why A Personal Financing Plan Matters
Households can face irregular income, changing expenses, major purchases, and unexpected repairs at the same time. A personal financing plan provides a process for deciding whether to save, borrow, use existing funds, or postpone a decision. It also helps separate urgent needs from expenses that can be planned over time.
Financial strength is not measured by income alone. Someone with a high income may still feel pressure if debt payments are large, bills are due before income arrives, or available cash is too limited to manage a surprise expense.
Step 1: Create A Clear Cash Flow Picture
Start with a practical record of money coming in and going out. Reviewing at least 3 months of bank, card, and loan activity can reveal recurring expenses that may not appear in a basic monthly budget.
Include These Cash Flow Categories
- Paychecks, business revenue, commissions, and side income
- Housing, utilities, groceries, transportation, and childcare
- Insurance premiums, taxes, and required account contributions
- Debt payments, interest charges, and annual fees
- Irregular expenses, including repairs, tuition, travel, and medical costs
- Savings and investment contributions
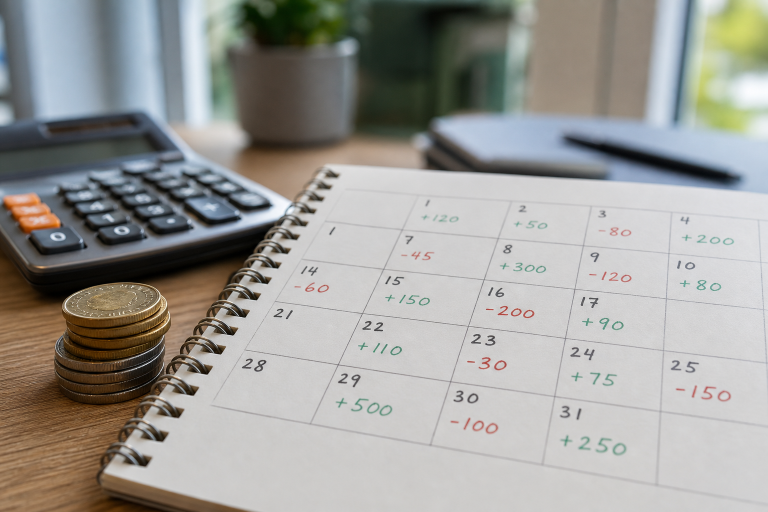
If income varies by season or commission cycle, use a weekly cash flow calendar. Monthly totals can look manageable while the timing of deposits and due dates still creates a short-term cash gap.
Step 2: Separate Liquidity From Long-Term Wealth
Liquidity means having funds that can be accessed promptly without selling an asset or taking on new debt. Retirement accounts, real estate, and insurance policies may hold value, but they are not automatically the right source for a bill due next week.
A dedicated reserve helps protect long-term plans from short-term disruptions. The cash reserve set aside for unplanned expenses should reflect your household's income stability, likely risks, and recurring obligations. Even a modest reserve can make it easier to avoid turning a one-time expense into a longer debt burden.
Step 3: Match The Financing Method To The Goal
Different needs call for different tools. Using long-term debt for a brief cash shortage can create an unnecessary obligation. At the same time, a large planned purchase may require a more structured approach than revolving credit can provide.
Common Financing Options To Compare
- Cash savings for smaller or planned purchases
- Personal loans for defined expenses with a stated repayment period
- Lines of credit for flexible access that remain controlled by a spending plan
- Home equity financing for significant, carefully evaluated expenses
- Business financing for equipment, inventory, expansion, or working capital
- Policy loans for eligible life insurance policies and suitable policyholders
Before choosing, compare the annual percentage rate, fees, repayment requirements, collateral, and the effect each option will have on normal monthly cash flow.
Step 4: Review The Risks Before Borrowing
Borrowing can solve an immediate problem while creating a later one. Consider what happens if income falls, a business has a slow period, expenses rise, or an asset connected to the loan loses value.
Questions To Ask Before Taking On Debt
- Can the payment fit within the normal monthly budget?
- Could the plan still work after three to six months of reduced income?
- Is the interest rate fixed, variable, or subject to future changes?
- Are there late charges, renewal costs, or early payoff fees?
- Does the arrangement place a home, a business asset, an investment, or a policy at risk?
- Will this debt reduce flexibility for a future priority?
Step 5: Understand Insurance-Based Borrowing
A policy loan is one possible financing tool, not a universal solution. Availability depends on the policy's cash value, contract provisions, insurer practices, and the policyholder's ability to maintain the coverage.
Loans generally reduce the value available in a policy and can affect the death benefit. With certain policies, loans can lower the cash value and contribute to a policy lapse if sufficient value is not maintained. Review the in-force illustration, loan provisions, premium requirements, and potential tax consequences with qualified professionals before relying on a policy for financing.
Step 6: Compare The Cost Of Keeping And Moving Money
Interest rates matter, but they are not the only cost. Opportunity cost matters too. Money used to pay down debt, fund a purchase, or support a policy loan cannot simultaneously remain in emergency savings or pursue another goal.
- Total interest and charges over the expected repayment period
- Upfront fees and ongoing account costs
- How much accessible cash remains after the decision
- Potential tax treatment and reporting responsibilities
- Effects on credit and future to cover short-term overspending, business assets, or insurance coverage
Step 7: Build A Simple Decision Checklist
- Define the exact purpose and amount needed.
- Calculate the total cost, including interest and fees.
- Measure the effect on monthly and weekly cash flow.
- Test the plan using a lower-income scenario.
- Compare at least two reasonable alternatives.
- Consult a qualified financial, tax, or legal professional when the decision is complex.
- Set a date to review the choice after it is in place.
Common Mistakes To Avoid
- Using long-term assets to repeatedly cover short-term overspending
- Focusing only on the monthly payment instead of the total cost
- Overlooking variable rates, fees, or renewal provisions
- Keeping too little cash available for genuine emergencies
- Assuming all life insurance policies have identical loan features
- Borrowing without a realistic repayment or monitoring plan
A Practical Example
Consider a household planning to replace essential business equipment. Rather than using all available savings, the household first determines the purchase price, maintains a separate emergency reserve, and compares paying cash with taking out a fixed-term loan or using an existing line of credit. The best choice is not necessarily the option with the lowest monthly payment. It is the option that addresses the equipment needs while allowing the household to meet regular bills and manage an unexpected setback.
How Often Should A Financing Plan Be Updated?
Review the plan at least annually and after a major financial change, such as a job transition, marriage, divorce, home purchase, new child, business launch, inheritance, retirement, or a substantial change in debt. Updating the plan keeps financing choices connected to current circumstances rather than outdated assumptions.
Conclusion
A dependable personal finance plan does not rely on a single product or strategy. It begins with accurate cash flow information, protects accessible reserves, evaluates risk honestly, and connects each decision to a clear purpose. Thoughtful planning can help you use savings, credit, insurance, and investments with greater control and fewer surprises.
Most read in News
Trending articles on News
Top articles on Minutehack


 Share article via email
Personal Financing: How To Balance Cash Flow, Risk, And Long-Term Goals
Thanks for signing up to Minutehack alerts.
Brilliant editorials heading your way soon.
Okay, Thanks!